Last week, the AI trade had one of its worst weeks since June with the PHLX Semiconductor Index down 11.4% (eight straight down days), while Nasdaq Composite lost 4.5%, and the S&P 500 dropped about 2%. At the epicenter of it was not even the chipmakers, rather the companies that borrow to rent the chips, which are commonly referred to as “neocloud” companies. CoreWeave, for example, which buys Nvidia hardware and funds it largely with debt secured by the chips and customer contracts, fell 15.5% on Wednesday alone after its unsecured bonds touched a 15% yield, although it did bounce back on Thursday when Nvidia CEO Jensen Huang defended the company; ultimately then dropped again Friday for a weekly decline of roughly 25%. The eight listed neocloud names averaged a 22% weekly loss, versus 6.6% for Nvidia itself.
The reason the buyers are hurting more than the suppliers is the higher borrowing costs. CoreWeave’s 9.75% notes due 2031 were trading near 82 cents on the dollar with a yield above 15%, up from roughly 12% two months ago, and its five-year credit default swaps hit a record of about 1,195bps, which implies a roughly 60% chance of default over five years. In its second quarter the company generated about $679 million in operating cash flow against roughly $6.4 billion of equipment spending, and its net interest expense, $640 million, had more than doubled. Management points to a $104 billion backlog and hopes to earn investment-grade ratings that would open insurer capital, but that plan looks fraught with peril in a higher for longer interest rate environment and when investors are demanding 15% for their bonds.
Many buyside shops have reaffirmed their positive views on the company and chip demand signals remain strong (ASML warned it may not be able to meet demand in 2027, and TSMC was expected to post profit growth near 60%). See below for a recent chart from Apollo on past and future expected AI spending from select hyperscalers:
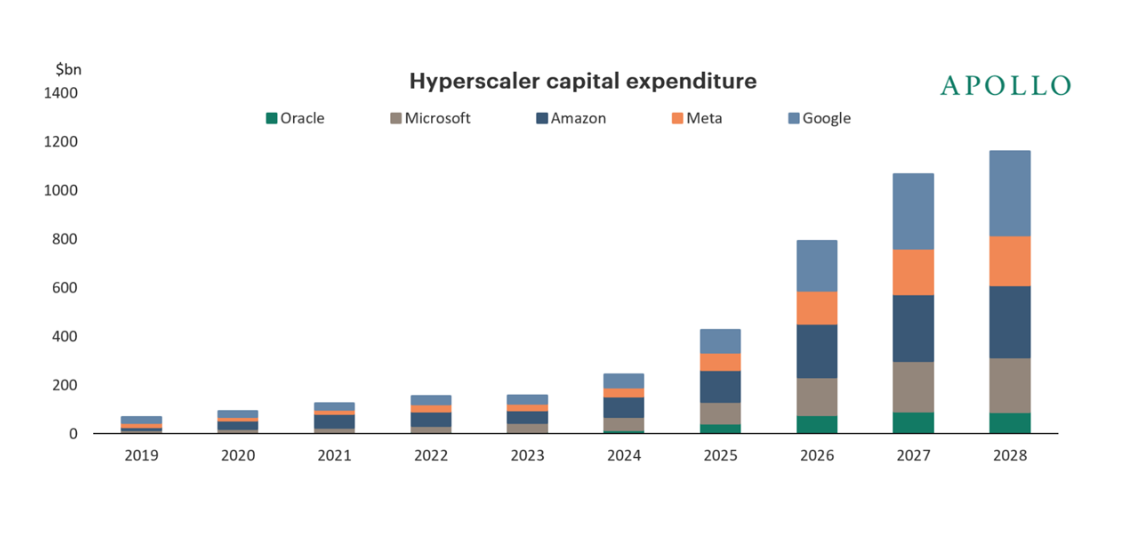
Source: Apollo
At the end of the day, AI is thrown around as a catch all, but there are fundamental differences in AI exposure. Chip designers with cash flow, hyperscalers, and highly levered data-center renters carry very different risks.
Earnings Season Starts Strong While Expectations Slip
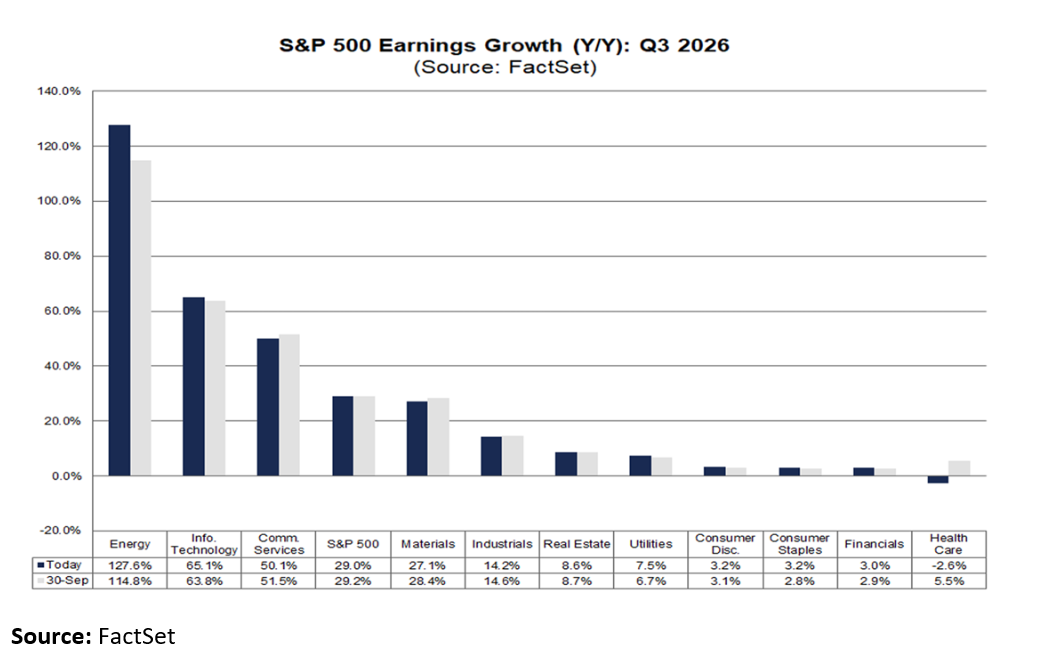
According to FactSet’s October 16 Earnings Insight, only 9% of S&P 500 companies have reported third-quarter results, so this is an early read. Of those, 84% beat EPS estimates, above the five-year average of 78% and the 10-year average of 77%, while 67% beat on revenue, roughly in line with the 70% five-year and 68% ten-year averages. The blended earnings growth rate is 29.0%, and the blended revenue growth rate is 12.6%. If those hold, it would be the third consecutive quarter of earnings growth above 25% and the eighth straight quarter of double-digit growth. With that said, earnings growth expectations have slipped slightly from 29.2% to 29% since the end of last quarter. See below for expected earnings growth by sector:
One factor many people aren’t talking about is that with the stronger earnings seasons and expected earnings in the future, valuations have come down. The forward 12-month P/E is 19.0, below the five-year average of 19.8 and close to the ten-year average of 19.1, so the market is not obviously expensive on forward earnings estimates. With 79 S&P 500 companies reporting this week, we should have a better sense of how earnings season is shaping up.
Credit Is Starting to Price in Risk, Especially CCC Rated Bonds
Most of the attention over the last month in the world of bonds has been focused on treasury yields, and for good reason. The 10-year touched 5.36% earlier this month, its highest yield since 2002. But the benchmark rate is only one part of what a company pays to borrow. The other is the credit spread, which is the extra yield investors demand over Treasuries to compensate for default risk, and that part has started to move too.
While we have seen repricing across the risk spectrum, it has been unusually pronounced for CCC rated bonds. See below for data on yields for bonds across the corporate credit spectrum:
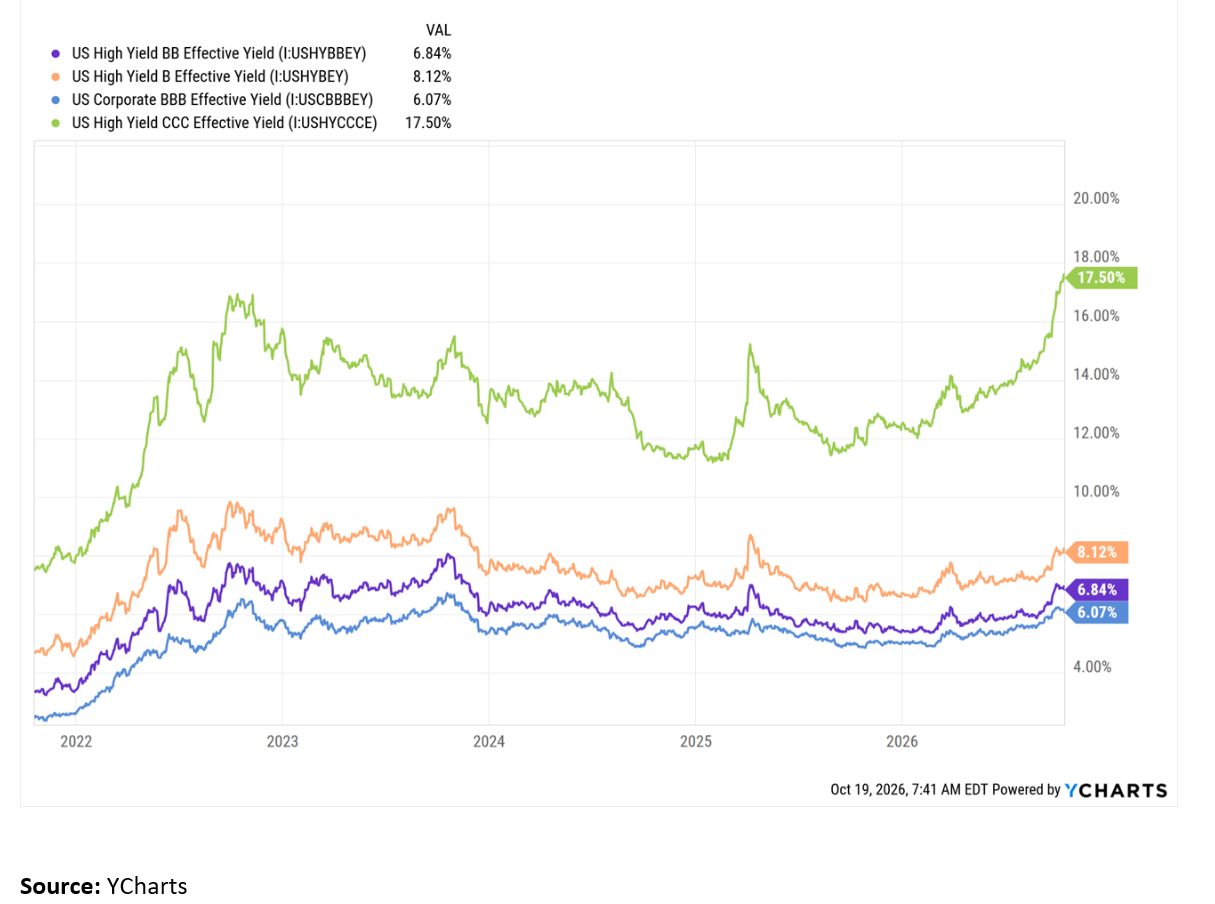
Looking at the chart, one would have to travel back to the peak of market frenzy in 2022 when all economists were forecasting a recession in the next 12 months to see total yields in CCC rated bonds this attractive.
So, what is driving the higher yields? The reasons are many. Much of the lowest-rated debt was issued in 2020 and 2021 at low rates and now has to be refinanced when the benchmark is above 5%, and recovery rates on recent defaults have been about 29%, well below the 25-year average near 40%. Cable and satellite, industrials, and packaging have led defaults, and distressed leveraged loans (those trading below 80 cents on the dollar) have climbed to about $140 billion, up nearly 90% in a year, with technology borrowers the largest share.
To put these numbers in historical context, it helps to remember that CCC is the riskiest rating tier and has always carried real default risk. S&P Global Ratings data covering 1981 through 2024 show that CCC/C-rated issuers defaulted at an average rate of about 26% within one year and about 47% within five years. By comparison, single-B issuers averaged about 2.9% (one year) and 15.6% (five years), BB issuers about 0.6% and 5.8%, and the entire speculative-grade universe about 3.5% and 13.6%. Those averages are heavily influenced by recessions, which is why default rates are so cyclical, but they are a reminder that a CCC bond has historically been risky.
Hope you have a great week, and remember, volatility is the price of admission.
Best,
Park City Investment Solutions Team
This material is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Opinions expressed are as of the date of publication and are subject to change. Past performance is not indicative of future results.